

Kosmos Energy’s 29.1% return over the past six months has outpaced the S&P 500 by 15.8%, and its stock price has climbed to $2.99 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Kosmos Energy, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Kosmos Energy Not Exciting?
Despite the momentum, we’re cautious about Kosmos Energy. Here are three reasons we avoid KOS, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
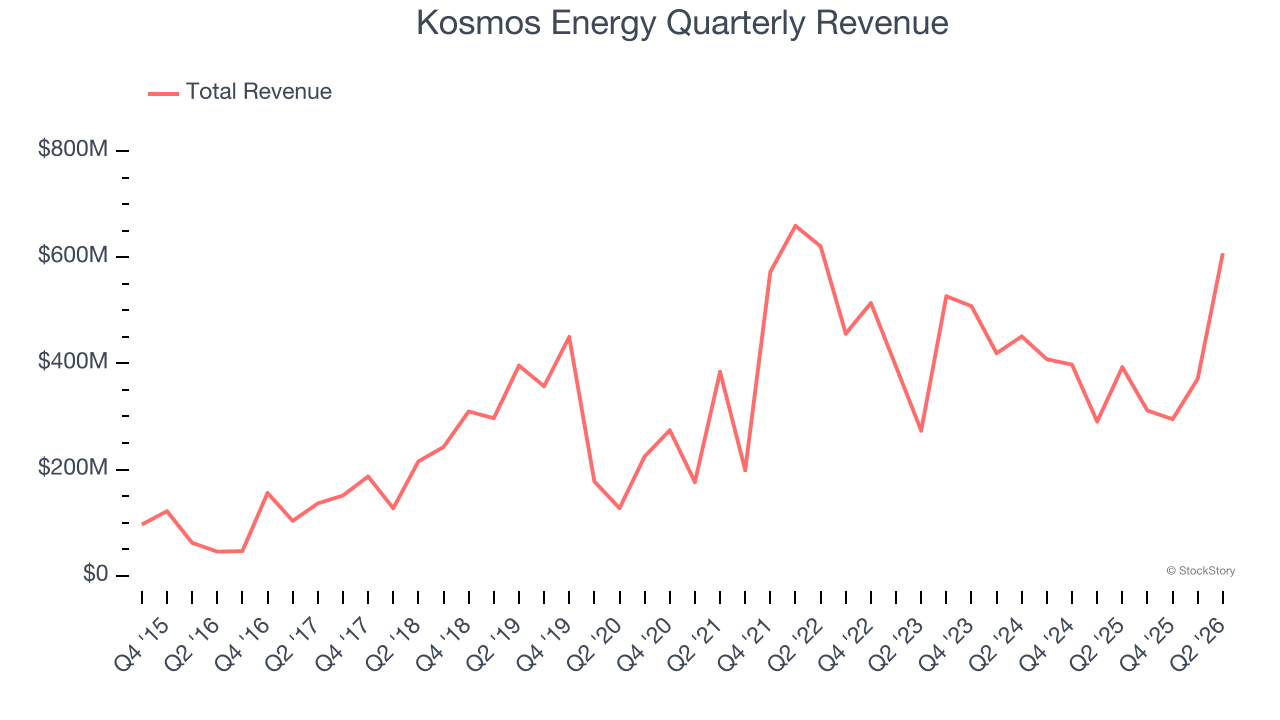
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Regrettably, Kosmos Energy’s sales grew at a tepid 8.4% compounded annual growth rate over the last five years. This was below our standard for the energy upstream and integrated energy sector.
2. Shrinking EBITDA Margin
Adjusted EBITDA margin is an important measure of profitability for the sector and accounts for the gross margins and operating costs mentioned previously. Unlike operating margin, it is not distorted by accounting conventions around reserves, drilling costs, and assumptions on commodity consumption from the well or basin. Adjusted EBITDA highlights the economic reality of how much cash the rock produces before the capital structure (debt service) and the drilling budget (capex) are considered.
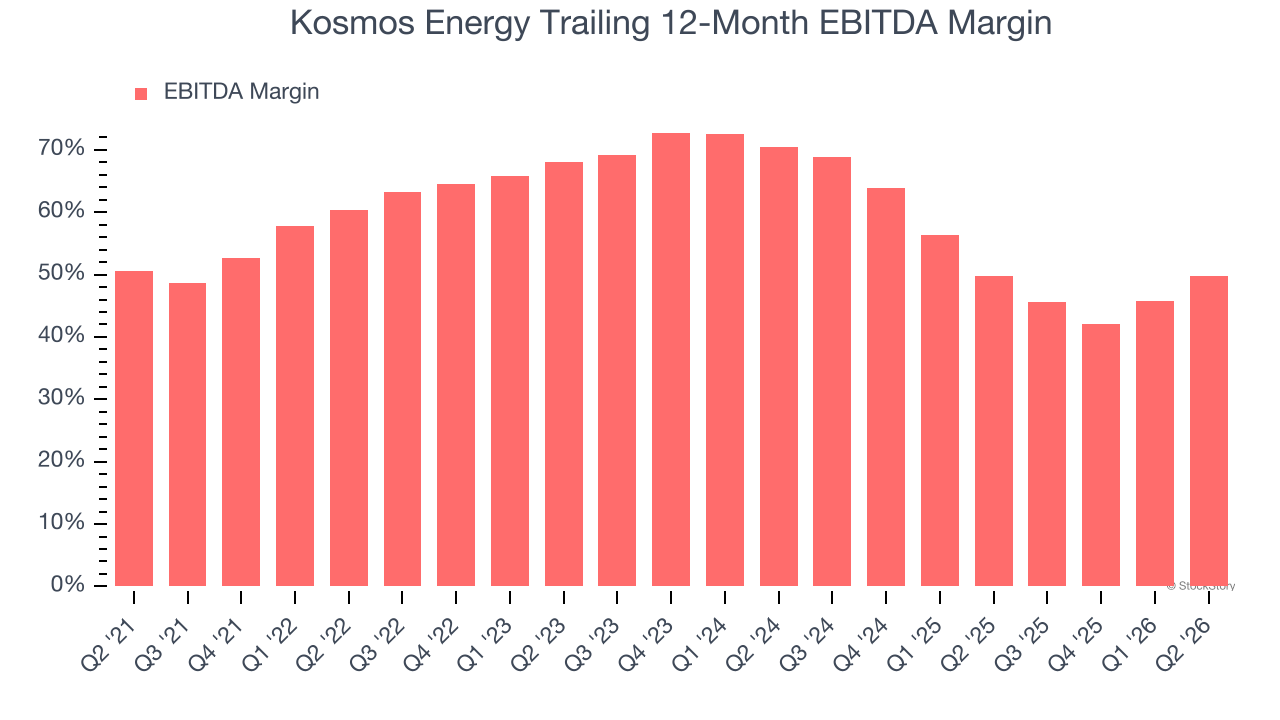
Looking at the trend in its profitability, Kosmos Energy’s EBITDA margin decreased by 10.5 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its EBITDA margin for the trailing 12 months was 49.8%.
3. Cash Burn Ignites Concerns
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
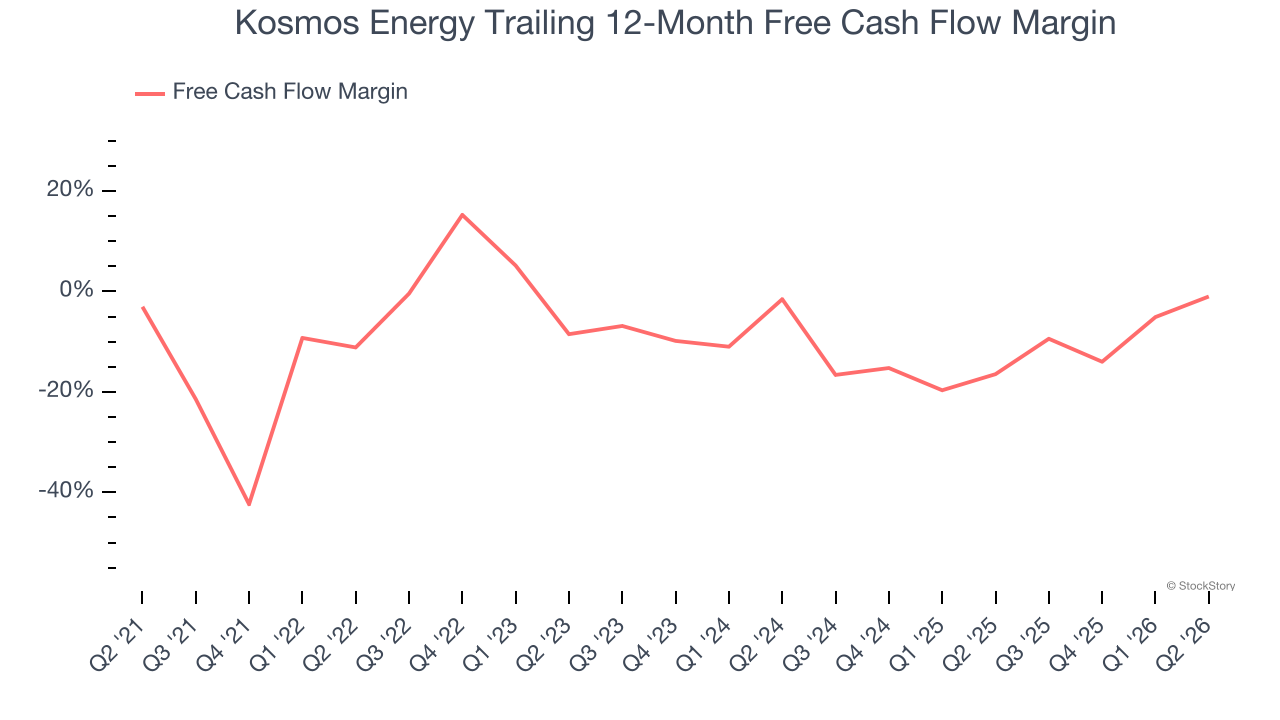
While Kosmos Energy posted positive free cash flow this quarter, the broader story hasn’t been so clean. Kosmos Energy’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 7.6%, meaning it lit $7.59 of cash on fire for every $100 in revenue.
Final Judgment
Kosmos Energy isn’t a terrible business, but it doesn’t pass our bar. With its shares outperforming the market lately, the stock trades at 7× forward P/E (or $2.99 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re fairly confident there are better investments elsewhere. Let us point you toward our favorite semiconductor picks and shovels play.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.